
Auto insurance
Two policies may cost about the same—and protect you very differently.
We compare options from multiple insurers to help you find coverage that fits your vehicle, your budget, and the way you want to protect it.
- Coverage
- Deductible
- Claim Payout
- Price
Step 1 of 2
We work with multiple insurance companies so we can compare your options.
What level of protection are you looking for?
Learn about the most common coverage options.
Exact coverage may vary depending on the insurer and the policy.
Comprehensive Coverage
Protection for third parties and your own vehicle.
- Physical Damage
- Total Theft
- Roadside Assistance
- Third-Party Liability
- Medical Expenses for Vehicle Occupants
- Legal Assistance
Additional coverage may be available depending on the policy.
Coverage, limits, deductibles, and services may vary by insurer, vehicle, and underwriting conditions. Your actual protection will always be determined by the terms of the policy you purchase.
Before you choose
Two “Comprehensive” policies can protect you very differently.
Even when two policies have the same type of coverage, important differences may become apparent when you need to file a claim.
Price isn’t the only thing that matters.What the policy includes—and how it responds—matters too.
Example for the Same Vehicle
Here’s how the terms can vary from one policy to another.
Same Vehicle
Same type of coverage. Different terms.
This example is for illustrative purposes only. Coverage, limits, deductibles, benefits, and terms may vary depending on the insurer, vehicle, and policy purchased.
Two policies may both be called “Comprehensive,” yet differ in what you pay, what you receive, and how they respond when you file a claim.
That’s why we compare the entire policy—not just the price.
Review options from multiple insurers for your vehicle.
All you need to get started is your vehicle’s model, year, trim, and ZIP code.
What would happen if…?
Your insurance can help in different ways depending on the coverage included in your policy.
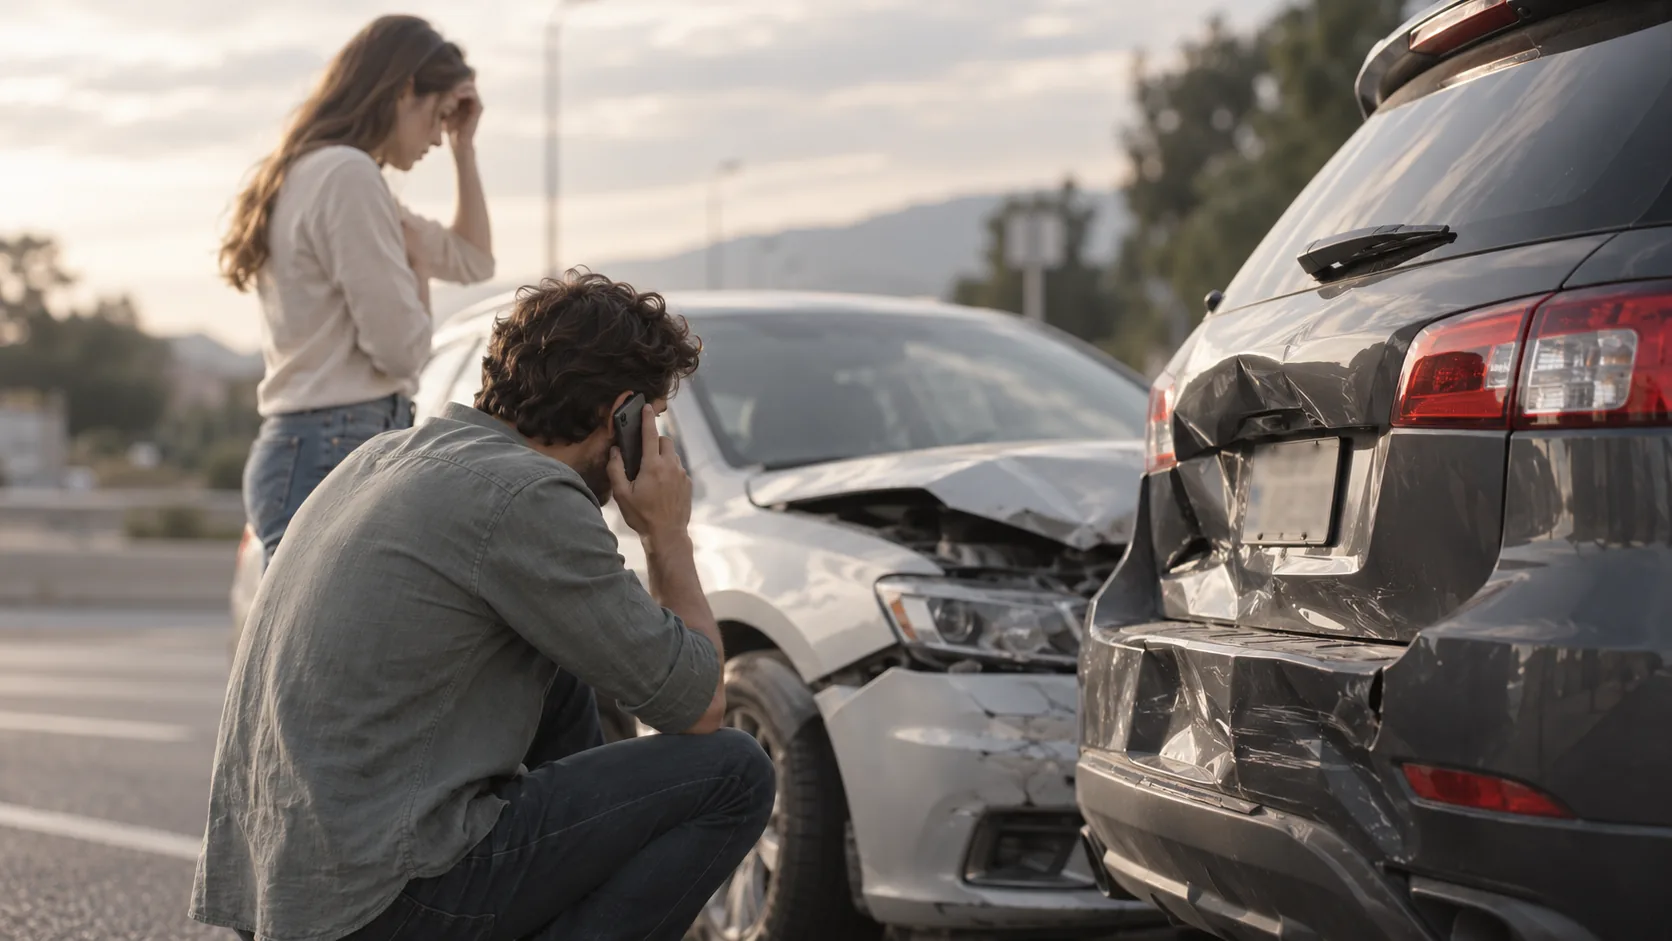
Physical Damage
You’re in an accident and your vehicle is damaged too
If your policy includes Physical Damage coverage, it may help pay for repairs to your vehicle after the applicable deductible.
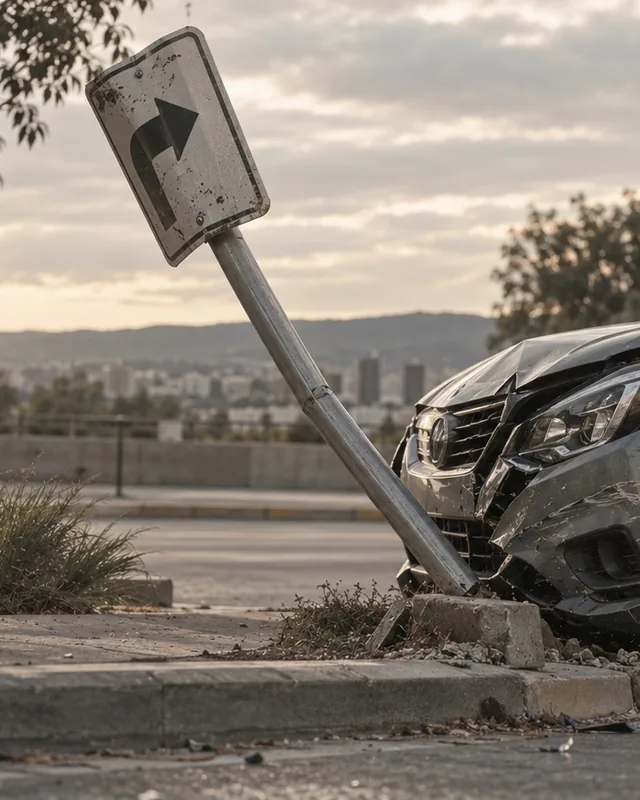
Third-Party Liability
You damage someone else’s property
For example, you hit a traffic sign, a fence, or someone else’s vehicle.
Third-Party Liability coverage may pay for property damage you cause to others, up to the coverage limit stated in your policy.
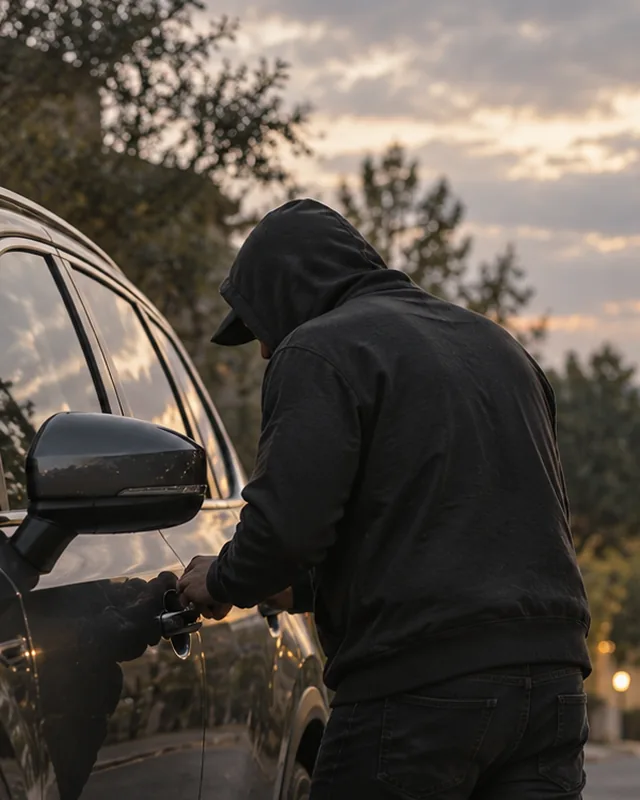
Total Theft
Your vehicle is stolen
If your policy includes Total Theft coverage, the insurer may compensate you based on the valuation method established in your policy, less the applicable deductible.
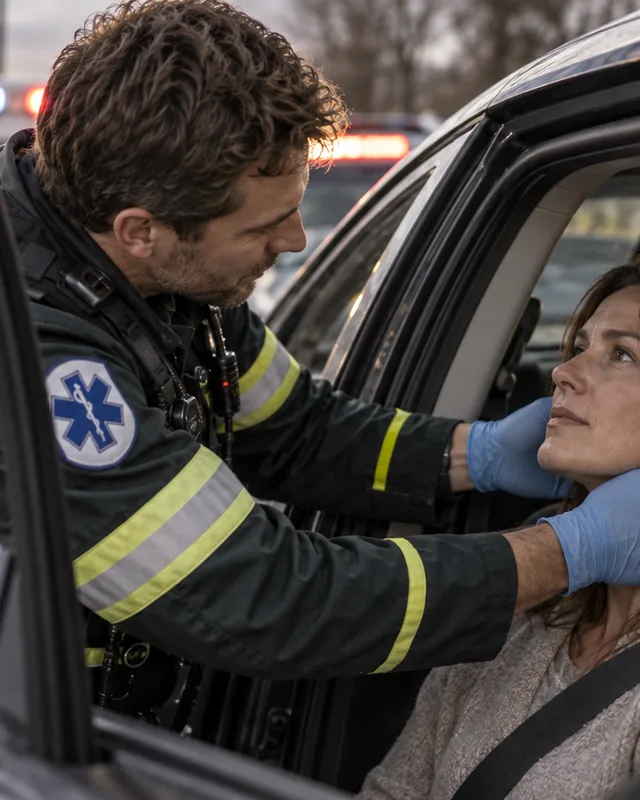
Medical Expenses
Someone inside the vehicle is injured
Medical Expenses for Vehicle Occupants may cover medical care for you and your passengers, up to the limit stated in the policy.
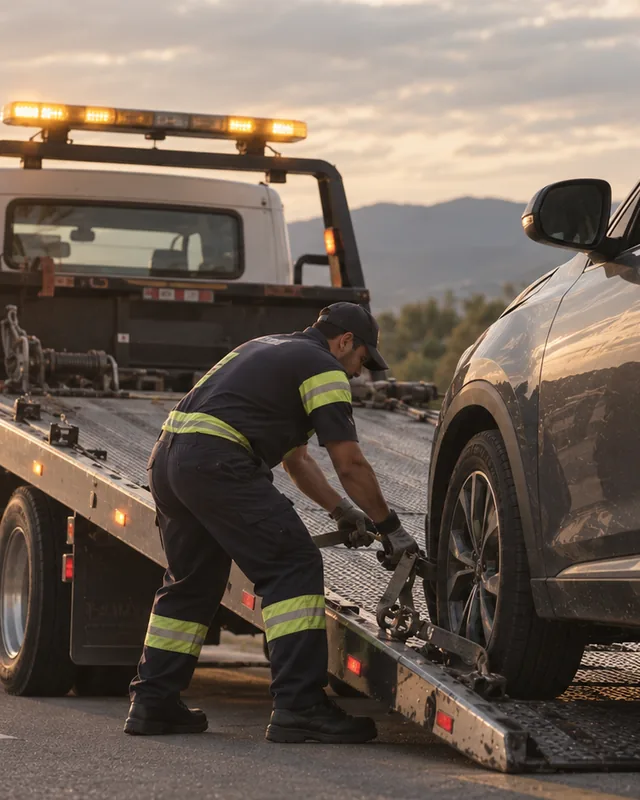
Roadside Assistance
Your vehicle breaks down
Roadside Assistance may include services such as towing, jump-starting a dead battery, or changing a flat tire, depending on the plan purchased.
Key concept
What is a deductible?
It is the portion of certain covered losses that you are responsible for paying when you file a claim.
Here’s an example:
Vehicle Value$300,000
You Would Pay
$15,000
Illustrative example only.
Deductibles You May Encounter
- Physical Damage
- Common deductible options may include 3%, 5%, or 10%.
- Total Theft
- The deductible may vary depending on the insurer, vehicle, and policy.
- Auto Glass
- A common reference is 20% of the cost of the glass.
A less expensive policy may come with a higher deductible.
These percentages are provided for reference only. The terms of the policy purchased will apply.
Claim payout
If your vehicle were declared a total loss, do you know how much it would be worth?
The amount may depend on the valuation method established in your policy.
01
Market Value
The vehicle’s value at the time of the loss is used as a reference, based on the criteria established in the policy.
02
Agreed Value
A specific value for the vehicle is established in advance.
03
Invoice Value
For certain vehicles and insurance products, the value shown on the original purchase invoice may be used.
The difference can matter a great deal when you actually need to use your insurance.
Frequently asked questions
Your questions, answered.
What is the difference between Comprehensive and Limited coverage?
Comprehensive coverage generally includes certain types of damage to your own vehicle, in addition to other protection. Limited coverage usually focuses on Total Theft, Third-Party Liability, and any additional coverage purchased. Exact coverage varies by insurer.
What is a deductible?
It is the portion of a covered loss that you are responsible for paying when you file a claim under coverage that includes a deductible.
Do all insurance companies use the same deductibles?
No. Percentages and amounts may vary depending on the insurer, vehicle, coverage, and policy terms.
Does my insurance protect me when I drive another vehicle?
Some policies include Extended Third-Party Liability coverage, which may protect you if you cause damage to others while driving a vehicle other than the one listed on your policy.
Depending on the policy, this protection may apply even if the other vehicle is uninsured, provided that the vehicle’s type, use, and circumstances meet the policy requirements.
Important: This extension generally covers your liability to third parties. It does not necessarily cover damage to the vehicle you are driving.
Does auto insurance cover hail or flooding?
Some policies cover these events under Physical Damage coverage or other specific provisions. It is important to confirm that they are included in the option you purchase.
What happens if my vehicle is declared a total loss?
Your claim payout will depend on the coverage purchased and the valuation method established for the vehicle, such as market value, agreed value, or invoice value.
Can I compare several insurance companies?
Yes. Because we work with multiple insurance companies, we can review different options and explain their differences to you.
Your vehicle is the same.
The policies aren’t.
We look for options from different insurance companies and help you understand the differences before you choose.
- Coverage
- Deductible
- Claim Payout
- Benefits
- Price
A better comparison.